
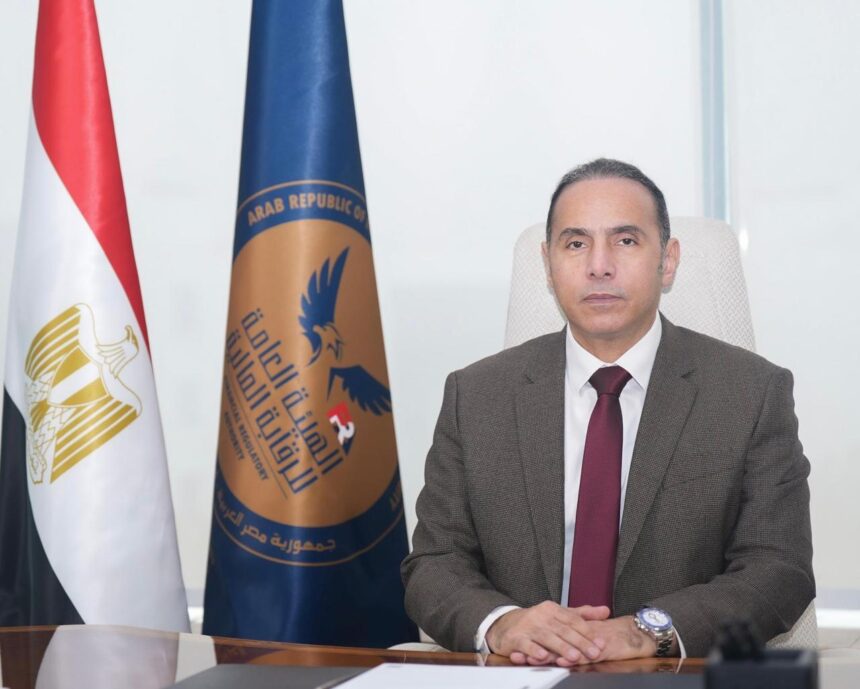
Islam Azzam, Chairperson of the Financial Regulatory Authority (FRA), has issued a decision introducing a comprehensive update to the rules governing the underwriting and pricing of credit and guarantee insurance policies.
The new rules aim to strengthen underwriting, pricing, reinsurance, and risk-management practices in the insurance sector, while ensuring greater discipline and financial stability in line with the nature and complexity of the risks assumed by insurers.
Decision No. 3132 of 2026 applies to property and liability insurance companies licensed to conduct credit and guarantee insurance, excluding commercial credit and guarantee insurance, whether domestic or export credit.
The decision establishes clear requirements for mandatory risk retention and the participation of credit providers in the risks covered by insurance policies.
Mandatory risk retention
The insured party or credit provider must retain at least 25% of the outstanding principal of the financing or credit facility insured by the insurance company at the time the insured risk materialises.
This portion may not be insured, redistributed, or transferred to a third party, directly or indirectly, in a manner that undermines the purpose of the retention requirement.
The FRA may impose a higher retention ratio for certain types of risks or portfolios based on risk indicators, loss and default rates, concentration levels, and the nature of the portfolio.
The decision also prohibits side agreements by the company, insured party, or credit provider, whether in the form of an agreement, addendum, undertaking, or other arrangement, if they directly or indirectly alter the scope of coverage, reduce or eliminate the retention ratio, amend the conditions for entitlement to compensation, or create rights or obligations that conflict with the insurance policy or FRA-approved endorsements.
No amendment to coverage, rights, or obligations may be recognised unless it complies with the rules governing the approval of insurance policies and products.
Underwriting policies and technical pricing standards
The decision specifies key elements that companies must include in their written credit and guarantee insurance underwriting policies, which must be approved by their boards of directors.
These include criteria for accepting and rejecting risks; methodologies for assessing creditworthiness; required retention ratios and collateral; maximum exposure limits; concentration limits for individual customers, related groups, credit providers, economic sectors, and types of financing; rules for monitoring defaults, recoveries, and collections; reinsurance policies; early-warning indicators; and measures to be taken when those indicators are breached.
Companies are also required to establish a technical and actuarial methodology for determining the minimum technical rate for credit and guarantee insurance policies, ensuring that premiums are sufficient to cover associated risks and costs.
When setting the minimum technical rate, companies must take into account several factors, particularly the probability of default (PD), exposure at default (EAD) where appropriate to the nature of the product, recovery rates, coverage ratio, retention ratio, financing or facility tenor, the nature and value of collateral, an uncertainty or risk margin, expenses, commissions, acquisition costs, and reinsurance costs.
The decision prohibits companies from issuing or renewing any policy at a rate below the minimum technical rate resulting from the approved methodology. This does not prevent companies from applying a higher commercial rate in accordance with their own policies.
Creditworthiness and pricing models
Regarding creditworthiness assessments, the decision sets out several factors that companies must consider when estimating the probability of default for individuals, legal entities, and project finance cases.
For individuals, companies must, at a minimum, consider the credit assessment issued by a licensed credit bureau, the debt burden ratio, and other statistically or actuarially significant variables.
Companies must calibrate the relationship between these variables and default rates based on reliable actual data and experience.
For legal entities and project finance, companies must use indicators appropriate to the nature of the risk when estimating the probability of default, particularly credit ratings or assessments, cash flows, liquidity and solvency indicators, debt-servicing capacity, collateral coverage ratios, and the economic sector and its associated risks.
Where reliable historical experience is available, companies must compare the cost of risk derived from the model used for pricing with the actual historical cost of losses incurred by the company on similar risks or portfolios.
This comparison must be conducted after standardising the basis of coverage and making the necessary adjustments to ensure comparability.
Companies must also conduct annual back-testing and periodic validation to assess the effectiveness of the model used to test rate adequacy and the accuracy of its forecasts.
To ensure the stability of the methodology and technical limits underpinning underwriting and pricing policies, the decision requires each company’s board of directors to approve, annually, an actuarial expert’s report covering the pricing methodology, minimum technical rates, assumptions and parameters used, calibration methodology, and the results of model testing and validation.
Before implementing the technical limits, companies must notify the FRA and provide the documents and data it specifies.
These must include a schedule of minimum rates according to the nature of the product, credit-rating bands, debt burden levels, type of collateral, coverage ratio, retention ratio, financing tenor, the actuarial expert’s report, the basis of calibration and supporting data, and the results of supervisory tests.
Companies must resubmit the study and technical limits to the FRA at least once a year, or whenever there is a material change in loss experience, default or recovery rates, underwriting policy, credit information methodology or source, actuarial methodology, or the assumptions or parameters used.
Concentration limits
The decision also requires companies to establish approved internal concentration-risk limits covering – at minimum, individual customers – related groups, credit providers, economic sectors, types of financing, and reinsurers, while complying with specified rules and ratios.
A company’s exposure to a single customer or related group may not exceed 10% of either the sums insured under the outstanding or in-force credit and guarantee insurance portfolio or the funds allocated to the branch’s liabilities, whichever is lower.
Business referred to an insurance company by a single credit provider may not exceed 50% of the branch’s sums insured in the case of banks and 30% for other credit providers, unless prior approval is obtained from the FRA.
Credit and guarantee insurance premiums may not exceed 25% of the company’s total premiums at the end of the year without prior FRA approval.
The FRA may approve an excess over any of these limits based on a technical and actuarial study covering, at a minimum, the impact of the excess on solvency, stress-test results, the quality of reinsurance, concentration levels, loss and default rates, and the company’s ability to absorb the risk.
Reinsurance and risk management
To further limit risk concentration and promote credit stability, the decision requires companies to ensure that their reinsurance programmes for credit and guarantee insurance portfolios are proportionate to the nature and scale of the risks they assume.
When designing reinsurance programmes and selecting reinsurers, companies must take into account the reinsurer’s solvency and credit rating, the size of the exposure, the recoverability of amounts due, and concentration risks, while avoiding unjustified material concentration with a single reinsurer.
Commenting on the new rules and their intended impact on Egypt’s insurance market, Azzam said the decision followed extensive industry and technical consultations with insurance and reinsurance companies.
He said the consultations reflected the FRA’s commitment to continuing to develop and improve the rules governing insurance activities in a way that safeguards companies’ financial stability, strengthens their ability to withstand market risks, and enhances their technical and professional efficiency, particularly given the vital role played by credit insurance policies in managing credit risk.
Azzam added that the new rules are detailed and clear and based on rigorous standards, while fully taking into account the provisions of Unified Insurance Law No. 155 of 2024 and the regulatory decisions issued by the FRA over the past three years.
The rules also keep pace with economic changes and developments in the sector by creating a regulatory framework for additional tools that support operational efficiency, he said.
Stress tests and qualified personnel
Azzam pointed in this regard to the decision’s requirement for companies to conduct stress tests and scenario analyses of their credit and guarantee insurance portfolios at least every six months and whenever there is a material change in the size or nature of the risks.
The tests are intended to assess default, recovery, and loss rates; the extent of concentration with a single financing provider; and the default or downgrade of a major reinsurer.
The rules also enable the FRA, where indicators of portfolio deterioration emerge, to require a company to submit and implement a corrective action plan.
Azzam stressed that companies must assign responsibility for underwriting, pricing, claims, and risk management within credit and guarantee insurance portfolios to personnel with experience and technical qualifications appropriate to the nature, scale, and complexity of the activity.
He said the FRA would issue a subsequent decision specifying detailed experience and qualification requirements to help improve technical efficiency.
The FRA will also issue the necessary decisions specifying the fundamental rules and standards required to implement the new requirements, including definitions of loss ratio, net exposure, related group, and net branch portfolio; early-warning indicators; the methodology for calculating concentration limits; definitions related to default; and the basic requirements for the actuarial methodology.
Standardised policies and credit information
Tarek Seif, Deputy Chairperson of the FRA, said the new rules include several significant developments that will help balance insurance companies’ portfolios, enable the early detection of risks regardless of their nature, ensure continuous updating based on clear technical standards approved by the FRA, and reduce loss ratios.
He added that the Insurance Federation of Egypt would play an important role in implementing the decision.
The federation will prepare draft standard terms and minimum requirements for the various forms of credit and guarantee insurance policies, including key definitions, scope of coverage, retention ratios, exclusions, conditions for entitlement to compensation, and other terms.
The draft will be submitted to the FRA for review and approval before implementation, making it easier for companies to apply the new requirements effectively.
Regarding the decision’s requirement that companies obtain a credit report on customers before issuing or renewing an insurance policy and use the results as part of the risk assessment, acceptance, and pricing process, Seif said the FRA would subsequently issue a decision defining default and restructuring cases, rules governing disputes over indebtedness, procedures for correcting, updating, and deleting information, data-retention periods, and rules governing data confidentiality and accessibility.
This will pave the way for the registration and immediate updating of data on defaults or payment stoppages through an electronic platform to be designated by the FRA.
Six-month compliance period
Companies will be required to bring their operations into compliance with the provisions of the decision within six months of its forthcoming publication in the Egyptian Gazette.
The decision will apply to policies issued for the first time or renewed after the end of the compliance period, without prejudice to rights and obligations arising from policies already in force.