
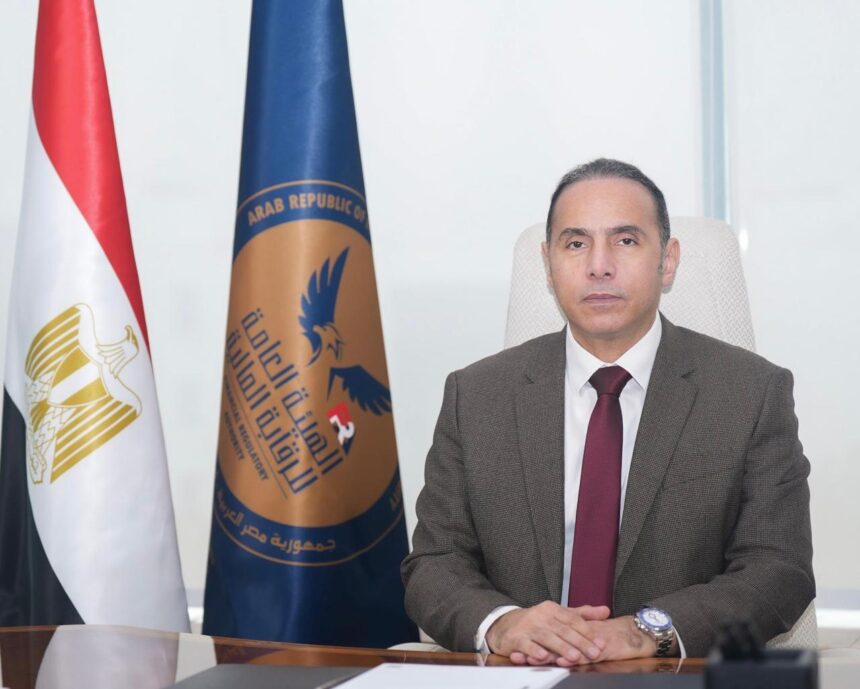
Islam Azzam, Chairperson of the Financial Regulatory Authority (FRA), has issued a circular to insurance companies aimed at enhancing disclosure and transparency for insurance policies incorporating investment strategies linked to gold, as part of the authority’s efforts to strengthen market oversight and protect customers’ rights across non-banking financial activities.
The circular requires insurance companies to clearly disclose the nature of their insurance products, prohibit misleading marketing and prevent confusion between insurance products and savings or investment vehicles. It also requires companies to document customers’ awareness of the nature of the insurance product.
The measures follow the FRA’s monitoring of a number of negative practices and complaints from customers concerning confusion during the marketing of insurance products through banking channels, particularly between insurance products and savings or investment vehicles, as well as banking products and services.
Under the circular, companies must disclose to customers, before entering into a contract and in a clear, accurate, and non-misleading manner, the insurance nature of the product, its benefits, risks, and key terms. They must also disclose any investment component or strategy linked to the product, enabling customers to make informed decisions.
Where an insurance policy includes an investment linked to gold or any other investment asset, the company must clarify the nature of the investment and how it is managed, and disclose the relevant fund or investment manager, where applicable.
Furthermore, the circular prohibits insurance companies from implying that they own or directly manage the underlying investment asset when this is not the case. Companies must clarify whether customers are entitled to receive or redeem the underlying asset in kind, along with any applicable delivery or redemption terms, as well as the basis for determining its liquidation or redemption value in accordance with the policy’s provisions.
The circular stresses that insurance companies must not use any statements, means, or marketing practices that could cause customers to confuse insurance products with deposits, accounts, or other banking products or services, or with savings and investment vehicles. It also prohibits marketing materials from containing false or inaccurate information or any information that could create an impression contrary to the product’s true nature or the terms approved by the FRA.
As an additional measure to protect and inform customers, the circular requires insurance companies to obtain and document a customer declaration before completing the contract. The declaration must confirm that the customer has reviewed the policy’s key terms and conditions; understands that the subject of the contract is an insurance product issued by the insurance company and is not a deposit, account, or banking product; and has received the information and disclosures necessary to understand the product’s nature, benefits, and risks.
The declaration must also confirm that the company has provided the customer with sufficient opportunity to enquire about the product’s terms and conditions.
Such a declaration does not exempt the insurance company from any of its legal or regulatory obligations relating to disclosure or the protection of customers’ rights.
According to the circular, insurance companies must review the marketing materials, forms, and methods used to distribute their products through banking channels and take the necessary internal procedures and controls to ensure compliance with the provisions.
They must also provide the FRA with details of the measures taken in this regard, along with the customer declaration form to be used during contracting, within one month.