
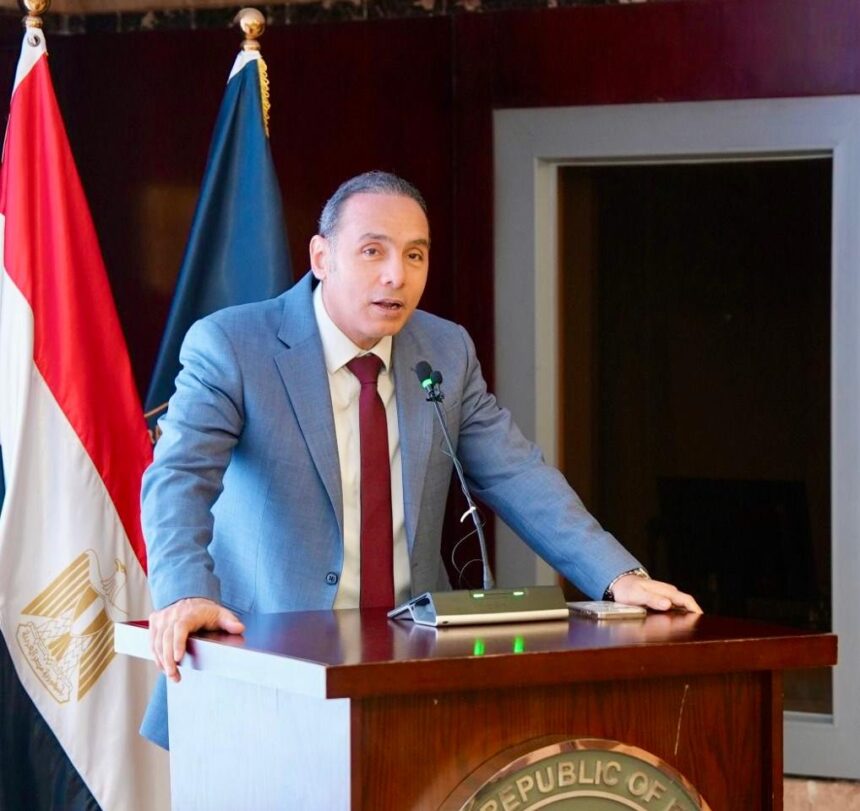
Islam Azzam, Chairperson of the Financial Regulatory Authority (FRA), has issued a decision requiring companies licensed to conduct consumer finance activities to obtain customers’ behavioural analysis scores based on alternative data through credit information company iScore and take the scores into account when making credit decisions to approve or reject financing applications.
Under Decision No. 2863 of 2026, companies are required to digitally verify the data of customers applying for financing (Digital Verification) and obtain their behavioural analysis scores based on alternative data (Behavioural Scoring Based on Alternative Data) provided by the credit information company.
The requirement supplements the existing controls governing customer data verification and digital identity requirements under FRA Board of Directors Decisions No. 140 of 2023 and No. 186 of 2024, and their amendments. It also complements credit enquiries into customers’ dealings with other banking and non-banking financing entities, in accordance with the Consumer Finance Law No. 18 of 2020 and the FRA’s relevant regulatory decisions.
Enquiries into customers’ behavioural analysis scores will begin on April 1, 2027, once the dedicated system at the credit information company is ready.
FRA Chairperson Islam Azzam said that digitally verifying customer data and obtaining behavioural analysis scores would help improve the efficiency of procedures for assessing customers’ creditworthiness, ensure the soundness of the credit-granting process, and reduce the likelihood of payment defaults.
Azzam added that the decision followed a series of consultative meetings with consumer finance companies and credit information company iScore. He stressed the FRA’s commitment to dialogue and consultation with industry stakeholders to enhance the sector’s stability and strike a balance between its expansion and growth and addressing emerging risks and challenges, including customer defaults and exposure to repayment risks that could adversely affect companies’ financial stability.
Moreover, he said activating the decision, alongside previous decisions concerning real-time connectivity between consumer finance and micro, small and medium enterprise (MSME) finance companies and the credit information company, as well as bringing forward the implementation of the customer identity verification system using one-time passwords (OTPs), represents an important step in the FRA’s ongoing efforts to develop the regulatory framework governing non-banking financial activities.
This forms part of a clear regulatory approach aimed at improving operational efficiency, financing decisions, and monitoring and supervision processes, while keeping pace with market changes, technological developments, and the evolving nature of risks.


